
Vesting Schedules in IMO Agreements: What They Mean
Vesting schedules in IMO agreements are the rules that decide what stays yours if the relationship ends. That sounds simple, but this clause often decides the real value of your renewals, overrides, and exit options long after the recruiting pitch is over. If you have ever glanced at an IMO contract at 4:45 p.m. before an onboarding call and focused only on comp, this is the section that deserves a second look.
What vesting schedules in IMO agreements actually mean
In plain English, vesting in the IMO context means your right to keep certain benefits after separation becomes stronger over time, or after hitting specific milestones. Those benefits can include renewal commissions, override income, deferred compensation, ownership-related rights, or other contract-based economics.
Here’s the part that trips people up: vesting schedules in IMO agreements are not mainly about what you get paid this week. They are about what you still get to keep later if you resign, get terminated, retire, switch uplines, or shut down production. A contract can look generous upfront and still leave you with very little once the relationship ends.
Think of vesting like earning the right to keep the back end of the deal. You may have already done the work that produced the business, but the agreement still controls how much of the future value remains attached to you.
Why vesting matters more than most agents expect
This is one of the most important sections in the contract. Not one of many equally important sections. One of the few that can quietly reshape the long-term economics of your whole book.
Two IMO contracts can offer similar commission levels and feel almost identical during the first few months. Then an exit happens, and suddenly one contract keeps renewals flowing while the other shuts them off, nets chargebacks forever, blocks hierarchy movement, or conditions everything on a broad “good standing” standard that was easy to ignore on page nine.
The short version of the risk
The risk is simple: headline comp can distract you from post-exit economics. A 10 point difference in street comp may matter less over time than a weak vesting clause tied to renewals, downline overrides, or termination rights.
That is why comparing offers means more than comparing percentages. It means asking what survives the relationship, what gets reduced, and what disappears.
What “earned” means versus what “vested” means
Earned usually means you produced the business that generated compensation. Vested usually means you have the contractual right to keep the related benefit, even after the relationship changes, subject to the rest of the agreement.
Those are not the same thing.
You can earn compensation through issued premium, placement, recruiting, or persistency. But the future economics connected to that production may still be unvested. For example, you may have earned a renewal stream by placing business, yet the contract may say only 40 percent of those renewals are vested if you leave before year three. That difference matters a lot once the contract stops being theoretical.
What an IMO agreement usually covers
An IMO agreement usually covers the business relationship between you and the marketing organization or uplink structure. In the life insurance world, that often includes street comp, overrides, renewals, chargebacks, debt balances, ownership claims, release terms, termination rights, hierarchy structure, and post-termination restrictions.
This is not generic employment law. In many cases, the real questions are distribution-specific: who controls the carrier relationship, who receives renewal income after separation, who can service the client, who can move the hierarchy, and who absorbs lapse-related losses.
Where the vesting language usually appears
Vesting language does not always sit in one neat section called “vesting.” Sometimes it shows up under compensation. Sometimes renewals. Sometimes termination, proprietary rights, indebtedness, or post-termination payments.
That means you cannot review one paragraph and assume you found the whole answer. The meaning often gets built across multiple sections, especially where definitions change how “renewals,” “cause,” or “book of business” are treated.
Why IMOs use vesting schedules in the first place
The business logic is easy to understand. IMOs use vesting schedules to improve retention, recover onboarding and support costs, discourage short-term production churn, and tie long-term payouts to persistency.
From the IMO side, that can be reasonable. If an organization spends money on contracting, compliance support, training, case design, marketing help, and management attention, it wants some protection against agents who write business quickly and leave before the economics settle out.
The catch is that the same clause that protects the IMO can heavily limit your long-term value if the relationship sours.
The main types of vesting schedules You’ll see
Not every contract uses the same structure. Once you know the basic types, the clause gets much easier to read.
Immediate or day-one vesting
Day-one vesting usually means your rights to specified compensation or renewals are fully vested from the start. In practical terms, if the contract ends, you may still keep the covered economics because no waiting period applies.
That sounds ideal, and sometimes it is. But day-one vesting does not magically erase chargebacks, debit balances, debt offsets, compliance issues, or post-termination restrictions. Full vesting can still exist inside a contract that gives the IMO broad offset rights or broad cause termination language.
Graded vesting
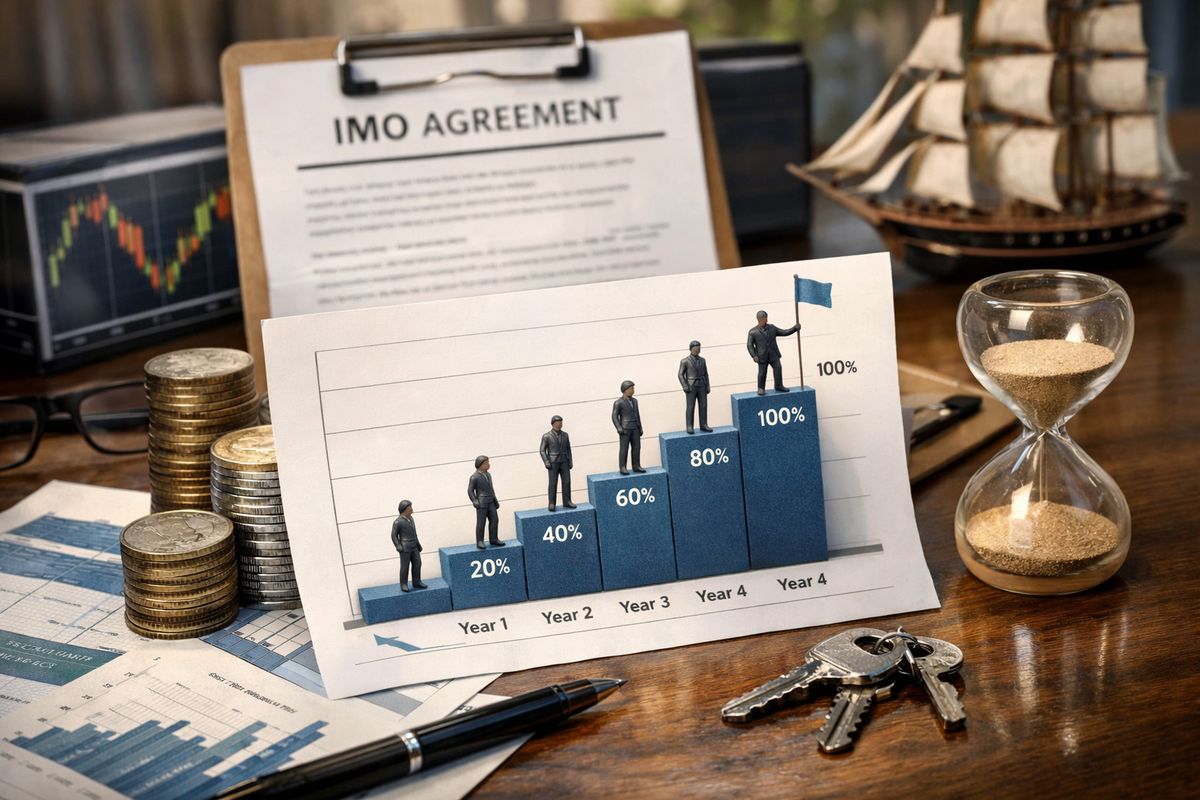
Graded vesting works in steps over time. A common structure might vest 20 percent per year for five years, or 25 percent after year one, 50 percent after year two, and so on.
If you leave partway through the schedule, you keep only the vested portion and lose the rest. Say your agreement provides a five-year graded schedule for renewals and you leave after two full years. You might keep 40 percent of eligible renewals and forfeit 60 percent. Exact treatment depends on how the contract defines service periods and termination timing.
Cliff vesting
Cliff vesting means nothing vests until a certain date or milestone, then a big portion vests all at once. For example, zero vesting until the end of year three, then 100 percent.
Early on, this can feel harmless because the relationship is new and departure is not top of mind. But at exit, cliff vesting can be painful. Leave one month before the cliff date and you may lose everything that would have vested just weeks later.
Production-based or milestone-based vesting
Some contracts tie vesting to premium volume, issued business, persistency, recruiting activity, or a mix of production and tenure. Instead of asking, “How long have you been here?” the clause asks, “What have you produced, and did it stick?”
That structure can reward strong, stable production faster than a calendar-based model. But it can also get messy if the milestones are vague. If “persistency standards” or “minimum production” are not clearly defined, the vesting test becomes harder to predict.
Hybrid schedules
Hybrid schedules combine time, production, and conduct requirements. For example, renewals may vest after two years only if chargebacks remain below a stated threshold, licenses stay active, and no cause event occurs.
These are common because they give the IMO several levers at once. They also deserve extra attention because a clean-looking timeline may hide extra conditions in another section.
What is usually subject to vesting
Vesting can apply to several separate rights. If you treat it as a single yes-or-no concept, you miss the real risk.
Renewal commissions
Renewals are the most common item tied to vesting schedules in IMO agreements. The contract may say your right to ongoing renewal commissions grows over time, becomes fully vested after a certain period, or continues only if you leave in good standing.
If you leave before full vesting, the unvested portion usually disappears. In some structures, even the vested portion remains subject to offsets for debt or chargebacks.
Overrides and downline compensation
Overrides on recruited agents or agency builders often have separate vesting treatment from personal renewals. You may be fully vested in your own renewals but only partially vested in override streams tied to downline production.
This gets especially relevant if you are building an agency. A strong top-line comp offer means less if the override stream vanishes when the hierarchy moves. If you want to go deeper on that issue, it helps to understand what happens to your team structure during a move.
Ownership of the book of business
This is one of the biggest misunderstandings. Vesting does not automatically mean you own your book.
A book of business includes more than one right. You may have an economic right to receive some renewals. That is not the same as controlling client records, servicing the policies, reassigning the business, or selling the book later. Economic rights, servicing rights, and relationship control can be split apart in the agreement.
Equity, bonuses, and deferred comp
Some larger organizations also use vesting concepts for retention bonuses, deferred compensation, equity-like interests, or bonus pools. These arrangements often look cleaner in recruiting conversations than in the actual contract.
If you see language around future payouts, earned equity, retention awards, or deferred balances, assume a vesting rule is attached somewhere.
Does “vested on day one” mean you get paid on day one?
No. Vesting and payment timing are different.
You can be vested in a right from day one and still receive payment later based on carrier cycles, commission statements, holdbacks, and reconciliation procedures. The right may be yours contractually, but the cash still moves on the schedule set by the carrier and the agreement.
Payment timing versus ownership rights
Ownership rights answer the question, “Do you get to keep this economic interest?” Payment timing answers, “When does money actually land?”
Those answers often live in different sections of the contract. One paragraph may grant vested renewal rights. Another may say payouts occur only after receipt from the carrier, subject to reserve holds, offsets, or periodic settlement.
Advances, holds, and reconciliation
Even favorable vesting language does not cancel the mechanics of commission accounting. Advances may be paid early and later reversed. Holds may delay payment pending policy issue or premium confirmation. Reconciliation may adjust prior statements after carrier corrections.
So yes, you can be fully vested and still see uneven cash flow. That is not automatically a contradiction. It is just a reminder that vested status and statement timing are separate issues.
How chargebacks interact with vesting
This is where many contracts get real, fast. A vested right can still be reduced by chargebacks, debt balances, offsets, or clawback provisions.
Vested does not always mean untouchable
Vested does not always mean protected from every deduction. It usually means the underlying right survives separation, but the amount paid can still shrink if the agreement allows the IMO to net obligations against that stream.
A vested renewal block can be whittled down by lapses, rescissions, premium refunds, advance recoveries, and debit balances. That is frustrating, but it is common.
Common offset language to look for
Watch for phrases that let the IMO apply “any amounts owed” against “any compensation due,” or that define indebtedness broadly enough to capture advances, chargebacks, fees, compliance penalties, or other alleged obligations.
Also watch for netting language buried in debt sections rather than compensation sections. If a contract says all commissions, renewals, bonuses, and other amounts may be offset against outstanding balances, your vesting clause may be less protective than it first appears. This is one reason many agencies spend time reviewing warning signs buried in contract language before focusing on comp grids.
What happens after termination
After termination, some agreements continue offsets until all chargebacks and debts are satisfied. Others cut off future commissions and still reserve the right to collect directly if ongoing compensation is not enough.
The timeline matters. Some contracts let offsets continue for as long as business remains on the books. Others set a collection period. Some allow direct invoicing or legal collection once post-termination commissions run out. If the contract is vague here, assume the broadest possible interpretation until clarified in writing.
What happens if you leave the IMO
This is where vesting stops being an abstract contract word and starts affecting actual money.
Voluntary resignation
If you resign in good standing, the agreement usually controls which vested rights continue, which unvested rights are forfeited, and how long post-termination payments last.
In the better versions, your vested renewals continue according to the schedule already earned, subject to normal offsets. In weaker versions, voluntary resignation still triggers loss of rights unless you meet extra conditions such as notice periods, release approvals, active licensing, or non-solicit compliance.
Termination for cause
Termination for cause is often where vesting gets cut down hardest. Contracts may suspend or eliminate otherwise vested rights if the separation involves fraud, replacements, compliance failures, debt, solicitation breaches, or conduct the IMO labels harmful.
The real issue is the definition of cause. Narrow cause language is one thing. Broad cause language that covers any policy violation, subjective reputational harm, or disagreement over procedures is something else entirely. Related restrictions often sit beside limits on recruiting or client outreach after departure, so the vesting section should never be read alone.
Retirement, disability, or death
Some agreements provide better treatment for retirement, disability, or death. You may see accelerated vesting, continued renewals to a beneficiary, or special servicing arrangements.
Check for beneficiary designations, succession rights, estate payment terms, and definitions of retirement. A contract may sound generous until you notice retirement means a narrow age-and-tenure combination that few people actually meet.
Moving to another IMO or direct-to-carrier model
A move to another IMO or a direct-to-carrier setup often creates the most practical friction. Even if renewals continue, release terms, carrier reassignment rules, non-solicit language, and hierarchy limitations can slow or block the transition.
That is why vesting should be reviewed alongside the mechanics of getting released and re-contracted cleanly. Keeping some economics is useful, but operational control during the move matters too.
Does vesting mean you own your book of business?
No. Not by itself.
Ownership of a book of business is really a bundle of rights. If your contract only addresses renewals, then your rights may be economic but not operational. You may get paid while still lacking control.
Economic interest versus control
Economic interest means you receive money from renewals or other ongoing business. Control means you can service the client, access the records, direct the relationship, influence reassignment, and potentially transfer or sell the asset.
Those are different things. You can have one without the other, which is why “vested renewals” should never be mistaken for full book ownership.
Carrier contract status matters too
Carrier appointment structure matters a lot here. Street-level contracts, agency-level contracts, and variations in appointment ownership can dramatically change what book control looks like in practice.
If the carrier relationship runs through the IMO in a way that limits your direct authority, your practical leverage may be smaller than your renewal rights suggest. That is also why disputes over ownership often spill into a bigger question about who actually controls the hierarchy and downstream relationships.
Assignment and transfer restrictions
Even if some rights are vested, the contract may still block assignment, transfer, sale, gifting, or collateralization of the book without consent. That can reduce market value because a book you cannot freely transfer is not the same asset as a fully portable one.
Read any clause that uses words like assign, transfer, sell, pledge, consent, or approval. Restrictions there can quietly limit what your vested rights are worth.
How taxes can complicate vested compensation
Tax treatment does not always line up neatly with how compensation feels in real life. That is the headache.
Vested renewals, advance commissions, debt forgiveness, and deferred comp can create tax timing issues that do not match the actual cash you keep. This is not tax advice. It is a reminder that contract economics and tax reporting can move on different tracks.
Cash received versus income reported
You may receive one amount, have offsets applied later, and still see tax reporting that reflects gross earnings or timing you were not expecting. That gap can be especially painful when chargebacks hit after year-end reporting has already occurred.
Review how statements, 1099 reporting, reserve holds, and reversals are handled. If the agreement uses advances heavily, cash flow and taxable income can drift apart faster than expected.
Chargebacks and prior-year earnings
A common pain point is paying tax on income in one period, then having part of it reversed later through chargebacks or clawbacks. Contract language does not solve the tax result by itself, but it does help you anticipate the pattern.
That matters because the emotional version of “I already earned it” is not the same as the accounting version.
How to read the vesting clause without getting lost
The easiest way to read this section is to stop looking for one magic paragraph. Instead, trace the whole path of the money and the rights attached to it.
Find the trigger events
Start by marking every event that changes vesting, reduces payout, or causes forfeiture. That usually includes resignation, termination, cause, debt, licensing lapse, production decline, compliance findings, non-solicit breaches, and carrier termination.
If a trigger event appears in another section, it still affects vesting even if the word vesting never appears there.
Match definitions across the contract
Definitions can quietly change everything. “Cause,” “renewals,” “book,” “termination,” “good standing,” and “indebtedness” may all be defined elsewhere, and those definitions often do the real work.
A short vesting clause attached to a broad cause definition is not really a short vesting clause. It is a long one wearing a disguise.
Check the order of operations
The sequence matters. Ask: does the agreement first calculate commission, then apply chargebacks, then determine vested percentage, then decide whether post-termination payments continue? Or does it determine vesting first and offset later?
That order can materially change what you receive. A contract that appears generous on percentages may feel much less generous once the offsets hit first.
Red flags hidden inside vesting language
Some problems jump off the page. Others hide in ordinary words.
“Sole discretion” wording
If the contract gives the IMO sole discretion to determine vesting eligibility, book ownership treatment, release approval, or cause findings, uncertainty goes up fast. Broad discretion is not automatically fatal, but it gives you less predictability when a dispute shows up.
In a good relationship, you may never feel it. In a strained one, you definitely will.
Vesting that disappears on broad “for cause” grounds
Fraud, theft, and serious misconduct are one thing. “For cause” that includes almost any policy violation, reputational concern, competitive activity, or disputed compliance issue is very different.
If broad cause language can wipe out vested rights, the schedule may be less valuable than it appears.
No clear schedule at all
If the contract says renewals may continue at the company’s discretion, or uses vague language about future participation without a defined schedule, do not treat that as vesting.
A real vesting schedule tells you what vests, when, and under what conditions.
Cross-default provisions
Cross-default language means a breach in one section can trigger penalties somewhere else. A solicitation issue, debt dispute, reporting problem, or confidentiality claim can become a vesting problem even if the vesting section looks clean on its own.
Those are the clauses that turn small disputes into large economic losses.
Questions to ask before you sign
A recruiting call is not the moment to stay vague. Plain questions save real money later.
What exactly vests?
Ask for a specific list. Renewals? Overrides? Servicing rights? Equity? Bonuses? Deferred comp? Some contracts use the word broadly in conversation and narrowly in writing.
If the answer is not itemized, assume less is covered than you were led to believe.
When does it vest?
Ask for the actual timeline or milestones. Is it immediate, graded, cliff, production-based, or hybrid? Does partial vesting apply? What happens if the agreement ends midyear or mid-cycle?
A clean answer should fit on paper, not just in conversation.
What can reduce or eliminate vested rights?
Ask directly about chargebacks, debit balances, cause termination, debt, production drops, licensing issues, compliance findings, non-solicit disputes, and carrier release problems.
This question often reveals more than the comp schedule does.
What happens if you leave in good standing?
Ask what continues after a clean exit. Do renewals keep paying? Do overrides continue? Can you keep carrier access? Can you service clients? How fast are payouts made? What has to happen before release?
Good-standing exits deserve as much attention as bad-breakup exits.
Can the terms change later?
Ask whether the vesting schedule can be amended unilaterally, what notice is required, and whether continued production counts as acceptance of new terms.
If a schedule can be changed later without much friction, its present value drops.
Example scenarios that make vesting easier to understand
A few realistic examples make the concept easier to hold onto.
New producer with a five-year graded vesting schedule
Picture a new producer who joins in March, writes steady business for two years, then exits to a different platform. The contract vests renewal rights at 20 percent per year over five years.
After two full years, 40 percent of eligible renewals are vested. The remaining 60 percent is forfeited. If the contract also allows chargeback offsets, even that 40 percent may be reduced until debit balances clear.
High producer with day-one vesting and heavy chargebacks
Now picture a high producer with full day-one vesting, excellent comp, and a rough block of business with significant lapse activity. On paper, the producer keeps renewal rights immediately.
In practice, the renewal stream gets chewed up by chargebacks and offsets tied to advances and policy fallout. Full vesting helps, but it does not erase the debit balance.
Agency builder with vested overrides but no book control
Last example: an agency builder has vested overrides on a downline but limited control over the actual client relationships and no independent reassignment power. After separation, some override economics continue, but servicing authority and practical hierarchy control stay elsewhere.
That can feel strange the first time you see it. But it is a common split between money rights and control rights.
Common myths about vesting in IMO agreements
A few myths show up over and over.
“If it’s vested, nobody can touch it”
Not true. Offsets, debt, chargebacks, clawbacks, and cause provisions can still affect what gets paid. Vested is stronger than unvested, but it is not always untouchable.
“Day-one vesting is always the best deal”
Not always. Day-one vesting inside a contract with broad offsets, weak release terms, or aggressive cause language can still be a worse overall deal than a slower schedule with cleaner post-exit rights.
“Vesting and ownership are the same thing”
They are not. Vesting usually addresses money or contract rights. Ownership of a book involves control, transferability, servicing authority, and carrier structure too.
“A higher comp level makes the vesting details less important”
This is probably the most expensive myth. Higher upfront comp can distract you from weaker long-term economics. A contract that pays more now but strips renewals or overrides later can be the worse deal by a wide margin.
A simple way to compare two IMO offers
Comparing two IMO offers is a lot like comparing two houses from the curb. The paint may look great on both. The foundation is what matters.
Compare the schedule
Start with the structure itself. Is vesting immediate, graded, cliff, milestone-based, or hybrid? A simple schedule is easier to value than one that depends on several moving conditions.
Compare the forfeiture triggers
Next, compare what can make vested or unvested rights disappear. Look at cause definitions, debt language, compliance triggers, production requirements, licensing status, and reassignment restrictions.
This section usually tells you how forgiving the relationship is when something goes sideways.
Compare post-exit economics
Then compare what happens after separation. Do renewals continue? Are overrides reduced? How are chargebacks handled? How long do offsets last? Who services the clients? If you are actively planning a transition, it helps to pair that review with a closer look at how agencies actually move from one IMO to another.
Compare control of the book
Finally, compare book control. Who has access to records, assignment power, carrier leverage, and transfer rights? This is where two similar comp offers can become completely different businesses.
The one thing to do before signing
Take one contract, grab a highlighter, and mark every place that mentions renewals, termination, debt, cause, ownership, chargebacks, and vesting. Then line those sections up side by side and read them as one system, not seven separate promises.
That one pass will tell you more about the real deal than the comp page ever will.
Insurance insights and tips




